Loans & net worth
What you own, what you owe, and what is still unknown. Nothing is estimated: a missing figure stays missing, and the page tells you which.
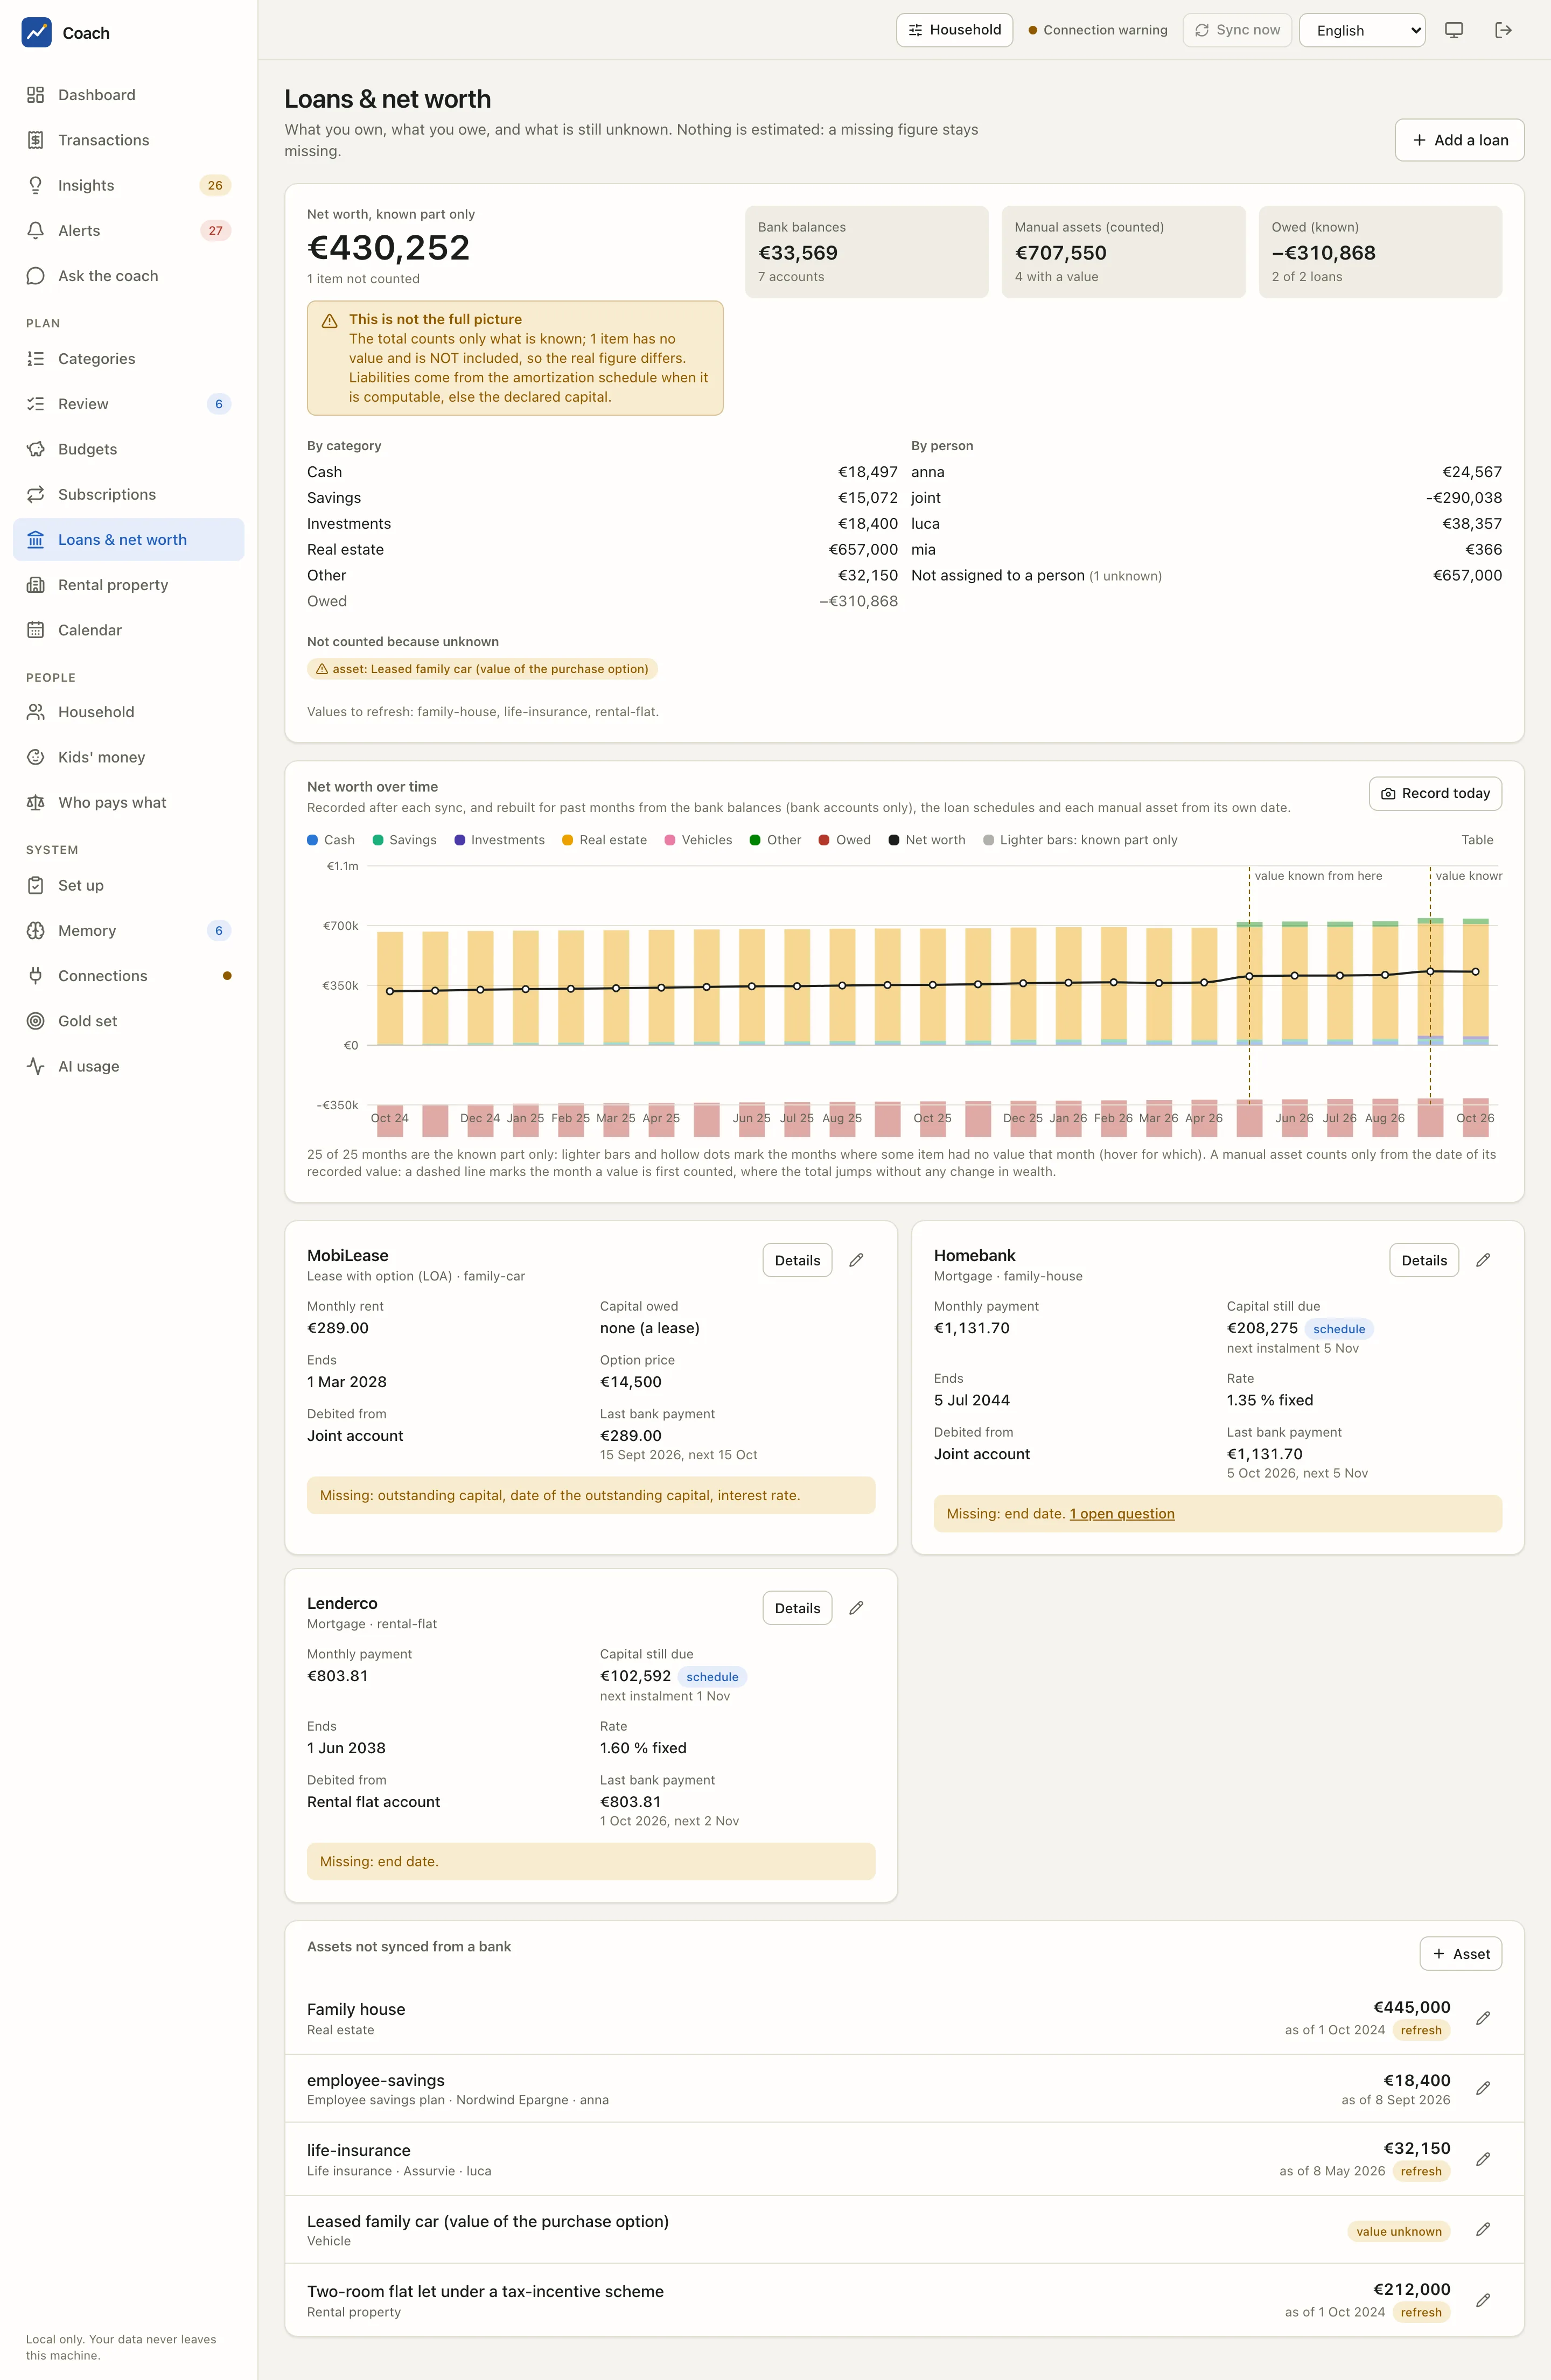
Net worth
Net worth, known part only = bank balances + manual assets with a value − what is owed on the loans. Next to it: Bank balances, Manual assets (counted) and Owed (known). The figure is split By category (Cash, Savings, Investments, Real estate, Vehicles, Other, Owed) and By person (the account owner, the holder of an asset or a loan, or joint).
Unknowns are listed, never guessed
An asset without a value, a bank account without a balance or a loan without a schedule is not counted, and the page says so: "This is not the full picture", with the list under Not counted because unknown. A total that left something out is never shown as your whole net worth, by the page or by the coach.
Values to refresh lists assets whose value is getting old.
Net worth over time
A monthly chart: assets stacked by category above the axis, what is owed below it, and the net-worth line. A snapshot is recorded after each sync, and past months are rebuilt where the data allow it: bank balances from the transactions, loans from their schedules, manual assets from their own date on.
- Lighter bars and hollow dots mark months where some item had no value (hover to see which).
- A dashed line ("value known from here") marks the month an asset is first counted. The total jumps there without any change in wealth.
- Record today stores today's snapshot on demand. Table gives the numbers.
Loan cards
One card per loan or lease: the monthly payment, the Capital still due with where it comes from (schedule when the amortization table can be computed, else the capital you declared), the next instalment, the end date, the rate, the account it is Debited from and the Last bank payment found. A yellow strip lists what is Missing ("Missing: end date. 1 open question").
For a lease (LOA / LLD) the card shows Capital owed: none (a lease), the monthly rent and the option price: a lease owes no capital, so its remaining rents are a commitment, not a debt.
Add a loan and the pencil open the loan form: kind, dates, amount borrowed, rate (fixed, variable, mixed), borrower insurance, deferral, the bank label of the payment, and the lease fields for a lease. Every save shows the diff first.
Details
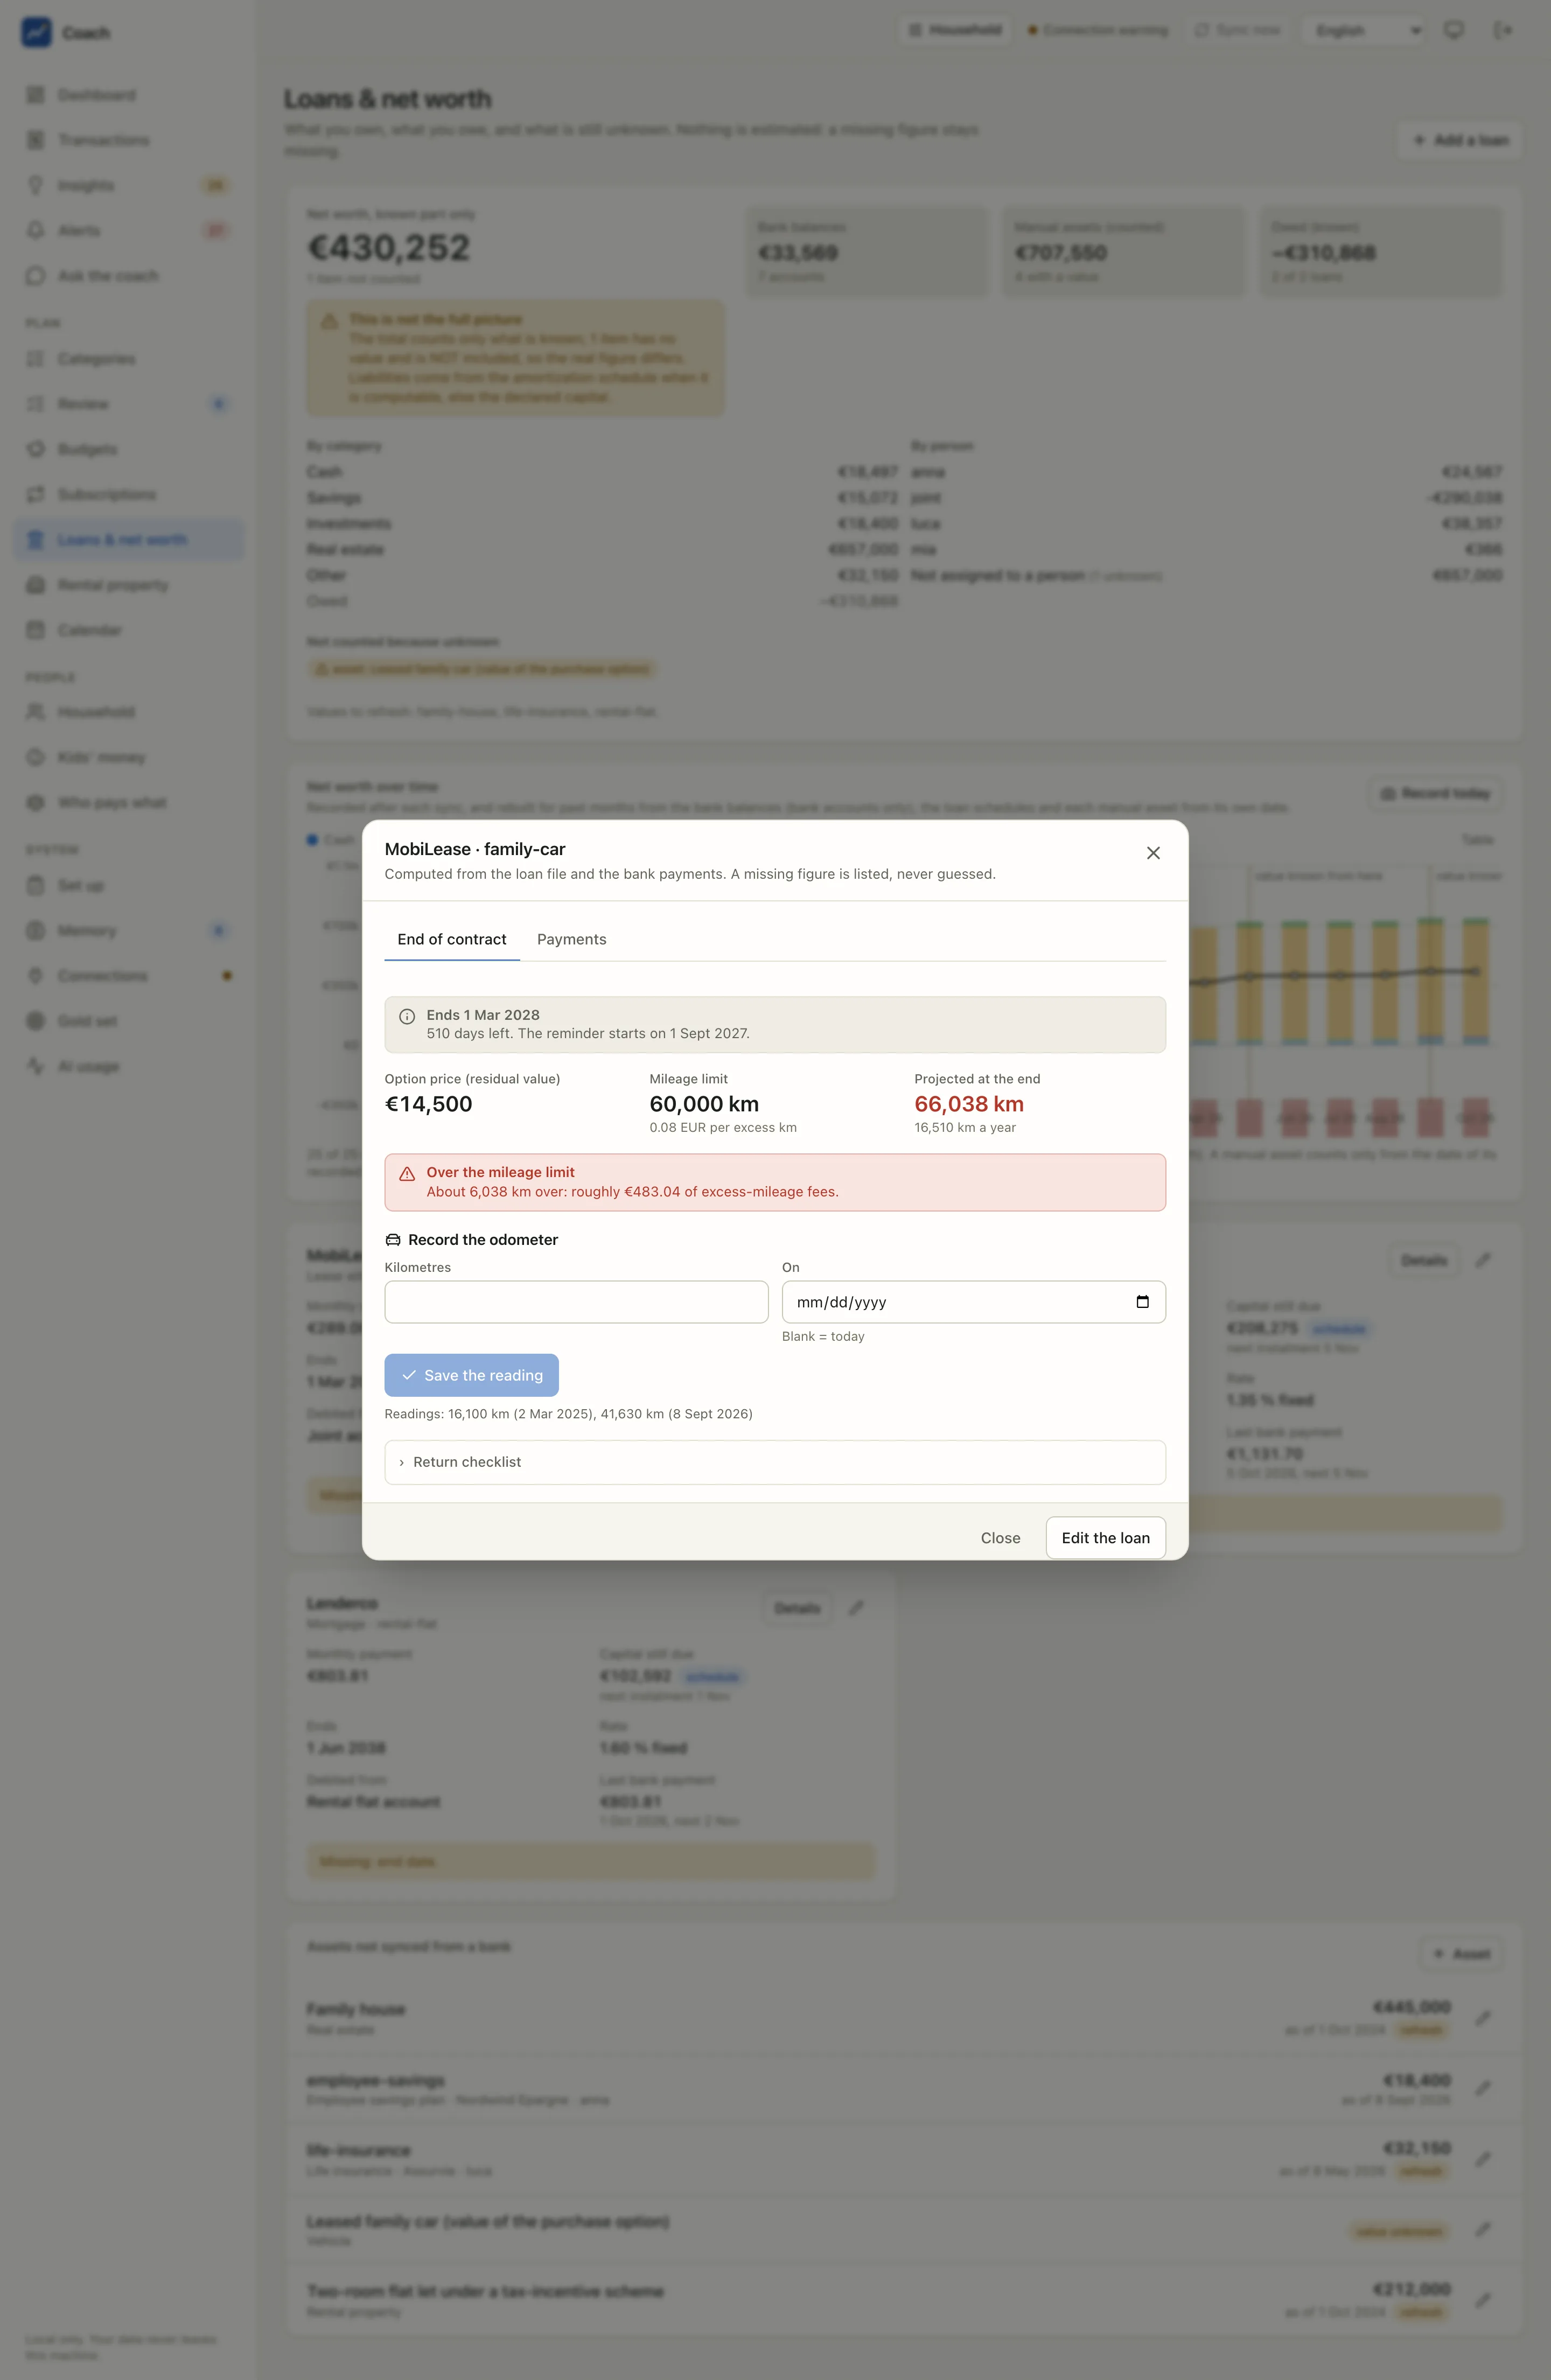
Details opens a dialog "computed from the loan file and the bank payments". Its tabs:
| Tab | What you find |
|---|---|
| Schedule | the amortization table: capital still due, instalments left, total cost, interest still to pay, and Interest by calendar year |
| Payments | the bank payments linked to the loan and its alerts |
| Scenarios | early repayment, renegotiation, insurance delegation |
| Suggestions | terms inferred from the payments, never recorded |
| End of contract | for a lease: the buy-or-return reminder and the mileage |
Interest by calendar year
It is the figure an Italian 730 mortgage-interest line or a French rental-income return asks for. Check it against the lender's annual statement before using it.
Payment checks
The app links each bank payment to its loan by its bank label and raises an alert when:
| Alert | When |
|---|---|
| missed payment | a due date plus a grace period (5 days) passed with no matching debit, and the account's data cover that date |
| amount changed | the last payment differs from the previous one or the schedule by more than 2 % and 1 EUR |
| extra payment | a debit far above the instalment, or a second one in a month: maybe a partial prepayment |
| wrong account | the payment left another account than the one on file |
When every instalment due was seen at the expected amount, the tab says so.
Scenarios
Estimates on the loan's real schedule (capital and instalments left, insurance, deferral). Nothing is changed anywhere, and the lender's figures decide.
An Amount to repay on a date, with the penalty from your contract (blank = the legal cap for a French or Italian mortgage). Two options are compared: keep the instalment and finish earlier, or keep the end date and lower the instalment. For each: interest and insurance saved, net of the penalty, and the break-even.
An Offered nominal rate and the Procedure (renegotiation with the same bank, buy-back by another bank in France, surroga in Italy), with bank and guarantee fees: the new instalment, the gross and net saving, and the break-even.
Another borrower-insurance policy (a dated quote for equivalent guarantees) and the switching fees: the monthly and net saving.
Store as an insight keeps the result in your Insights. Every scenario is general information, not financial advice; the app names no lender or insurer.
Suggestions: inferred, not recorded
When some loan terms are missing, the app can work them out from the instalments seen in the bank data (annuity maths), with a confidence level. These values are never written to your memory: Queue as a memory proposal creates a proposal that you check against the contract and accept yourself in a terminal.
End of contract (leases)
The end date and the reminder 6 months before it (decide between buying and returning the car), the Option price (residual value), the Mileage limit and the fee per excess km, and the mileage Projected at the end from your readings. Record the odometer adds a reading. A Return checklist lists the usual steps; verify the notice and return conditions in your own contract.
Assets not synced from a bank
The house, an employee savings plan, a life-insurance contract, the leased car, a rental flat: each with its value and the date of that value. A refresh badge marks a value that is getting old; value unknown marks one you never gave (and that is therefore not counted). Asset adds one.
From the terminal
uv run coach networth --history
uv run coach loans list
uv run coach loans schedule <id>
uv run coach loans payments <id>
uv run coach loans scenario prepay <id> --amount 10000
uv run coach loans infer <id>              # suggestions, never written (--propose queues a proposal)
uv run coach loans lease <id>
coach loans add, edit and odometer preview the change and write after a typed yes in your terminal.
See also
- Loans reference: the loan record, inference, schedules, net worth and scenarios.
- Rental property: a loan that finances a rental flat.
- Memory & set-up: the loan, contract and asset forms.