Rental property
The real return of a rental flat and the obligations of the tax-incentive scheme it sits in, computed from its bank account, its loan schedule and the facts you recorded.
Your figures, never looked up
Every scheme figure (rent cap, tenant income limit, reduction rate, market rate, valuation) is the one you typed from your deed or a quote. Nothing is looked up on the web and nothing is guessed: a missing fact is listed and becomes an open question.
Setting it up
A property is an asset of kind "rental property" in your memory, linked to its bank account (purpose rental) and to the loan that
financed it. Declare a property creates one (use an id with no address in it); Edit facts adds the scheme, the rent, the price and
the commitment. The property's flows are labelled by generic rules: rent received, loan instalment, co-ownership charges, property tax,
management fees, landlord insurance (PNO, GLI). A cost paid from another account counts when you tag it property-<id>.
The page is about the whole household: the person switch does not narrow it, and a child login cannot open it. With several properties, a switch picks one. The tabs are Cash flow and P&L, Scheme commitment, Tax year and Renegotiate or sell.
Cash flow and P&L
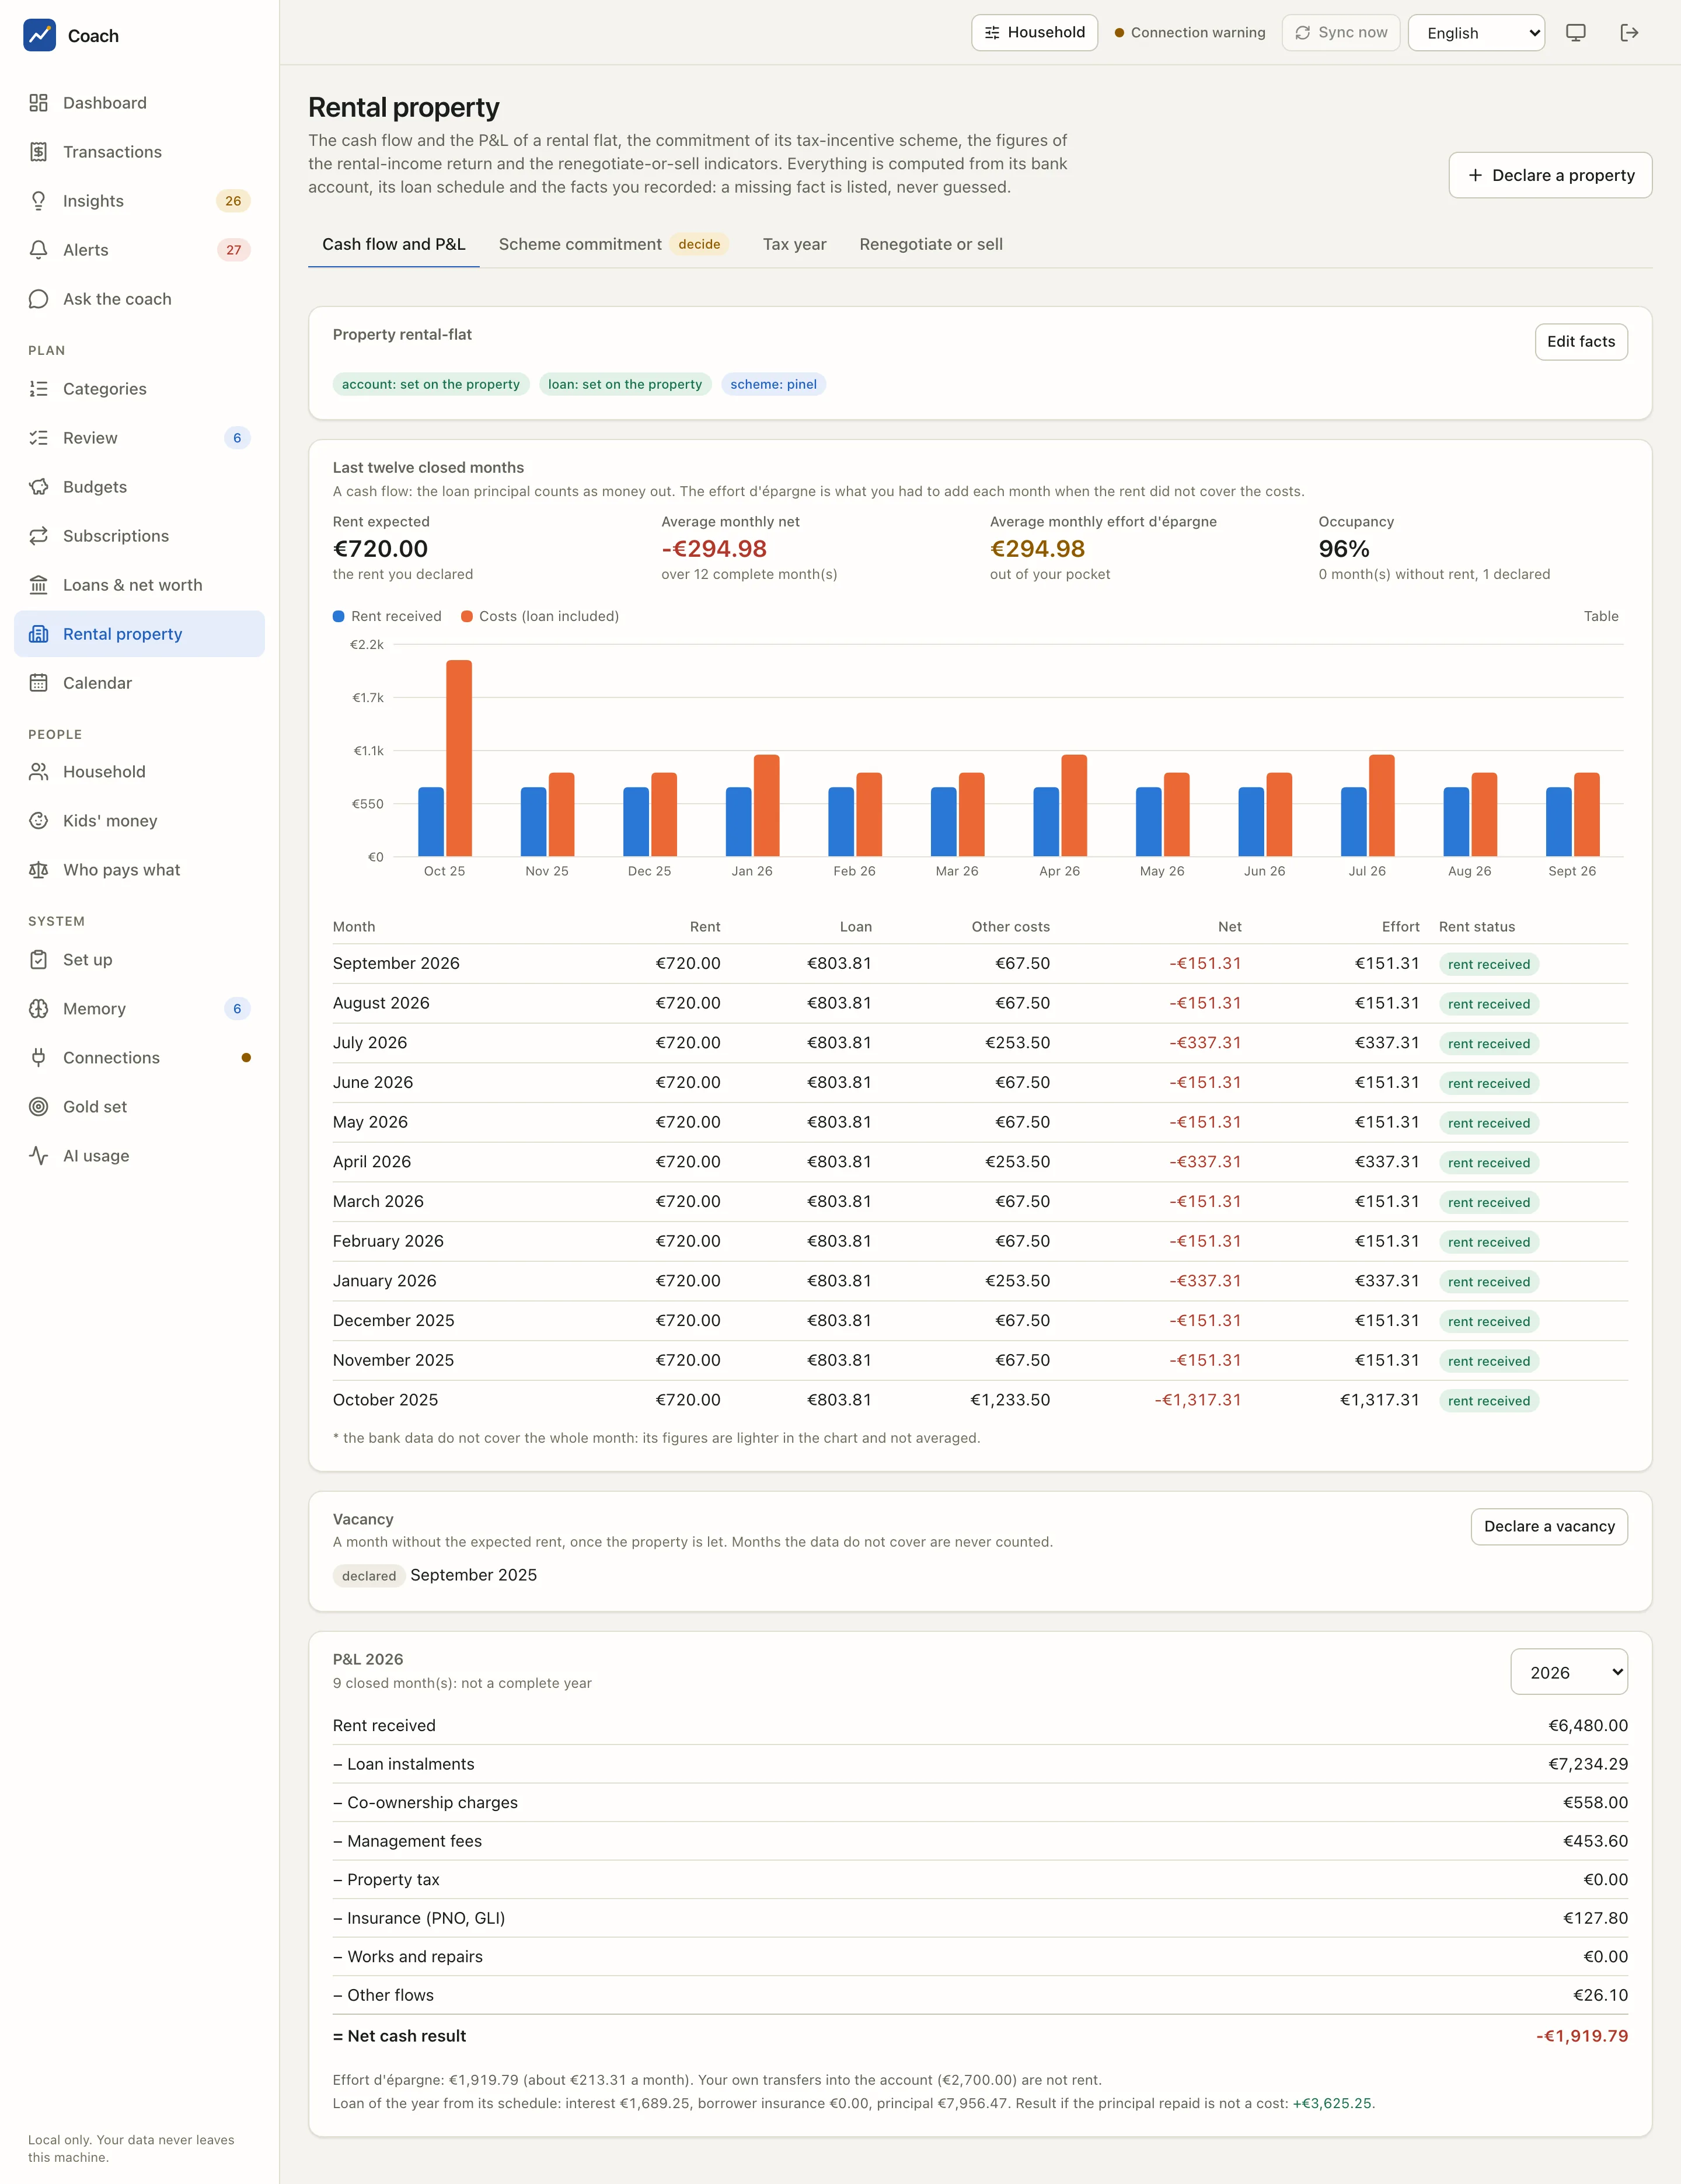
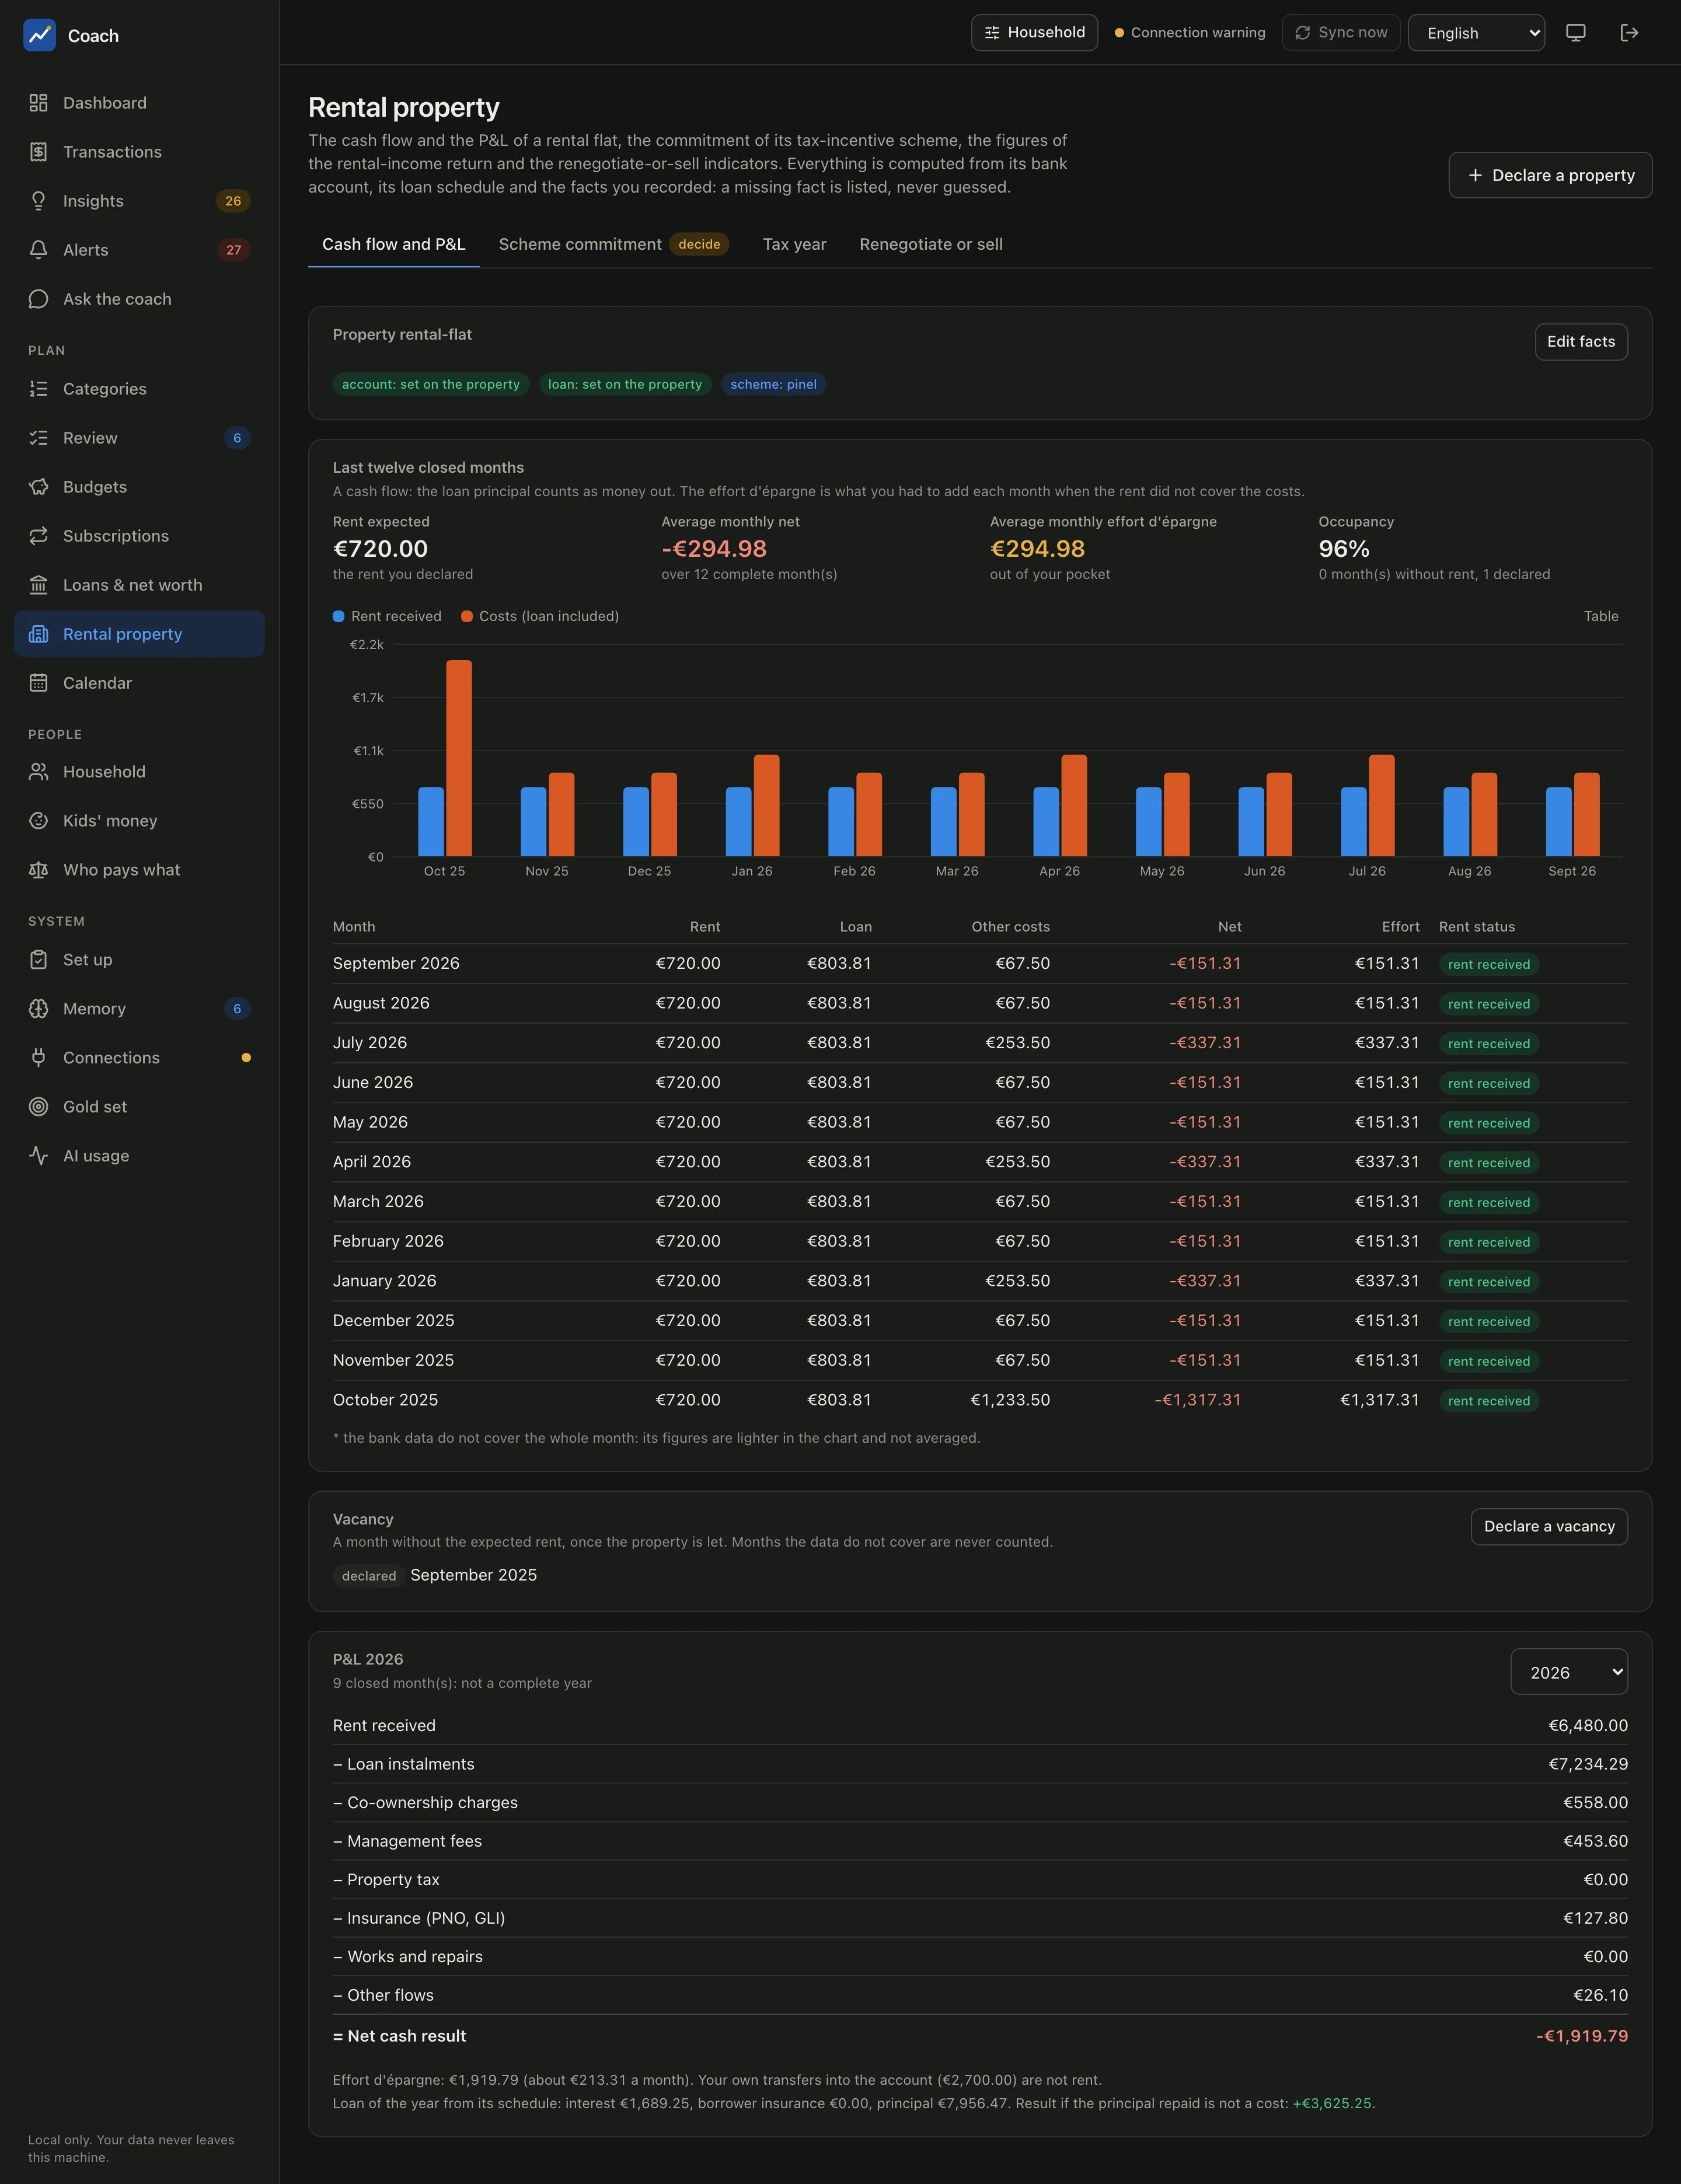
Last twelve closed months is a cash flow: the loan principal counts as money out.
| Figure | Meaning |
|---|---|
| Rent expected | the rent you declared |
| Average monthly net | rent minus every cost, loan included, over the complete months |
| Average monthly effort d'épargne | what you had to add each month when the rent did not cover the costs: out of your pocket |
| Occupancy | the share of months with rent, with the months without rent and those you declared |
The chart shows Rent received against Costs (loan included), and the table each month's rent, loan, other costs, net, effort and Rent status (rent received, partial, late, declared vacancy...). A month the account data do not fully cover is drawn lighter and never averaged.
Vacancy lists the months without the expected rent once the property is let. Declare a vacancy records a period you know it was empty (works, between two tenants), so it is not reported as a missing rent.
P&L of a year (pick it in the selector): rent received, loan instalments, co-ownership charges, management fees, property tax, insurance, works and repairs, other flows, and the Net cash result. Under it, the loan of the year split into interest, borrower insurance and principal from the schedule, and the result if the principal repaid is not counted as a cost. Your own transfers into the account are never rent.
Scheme commitment
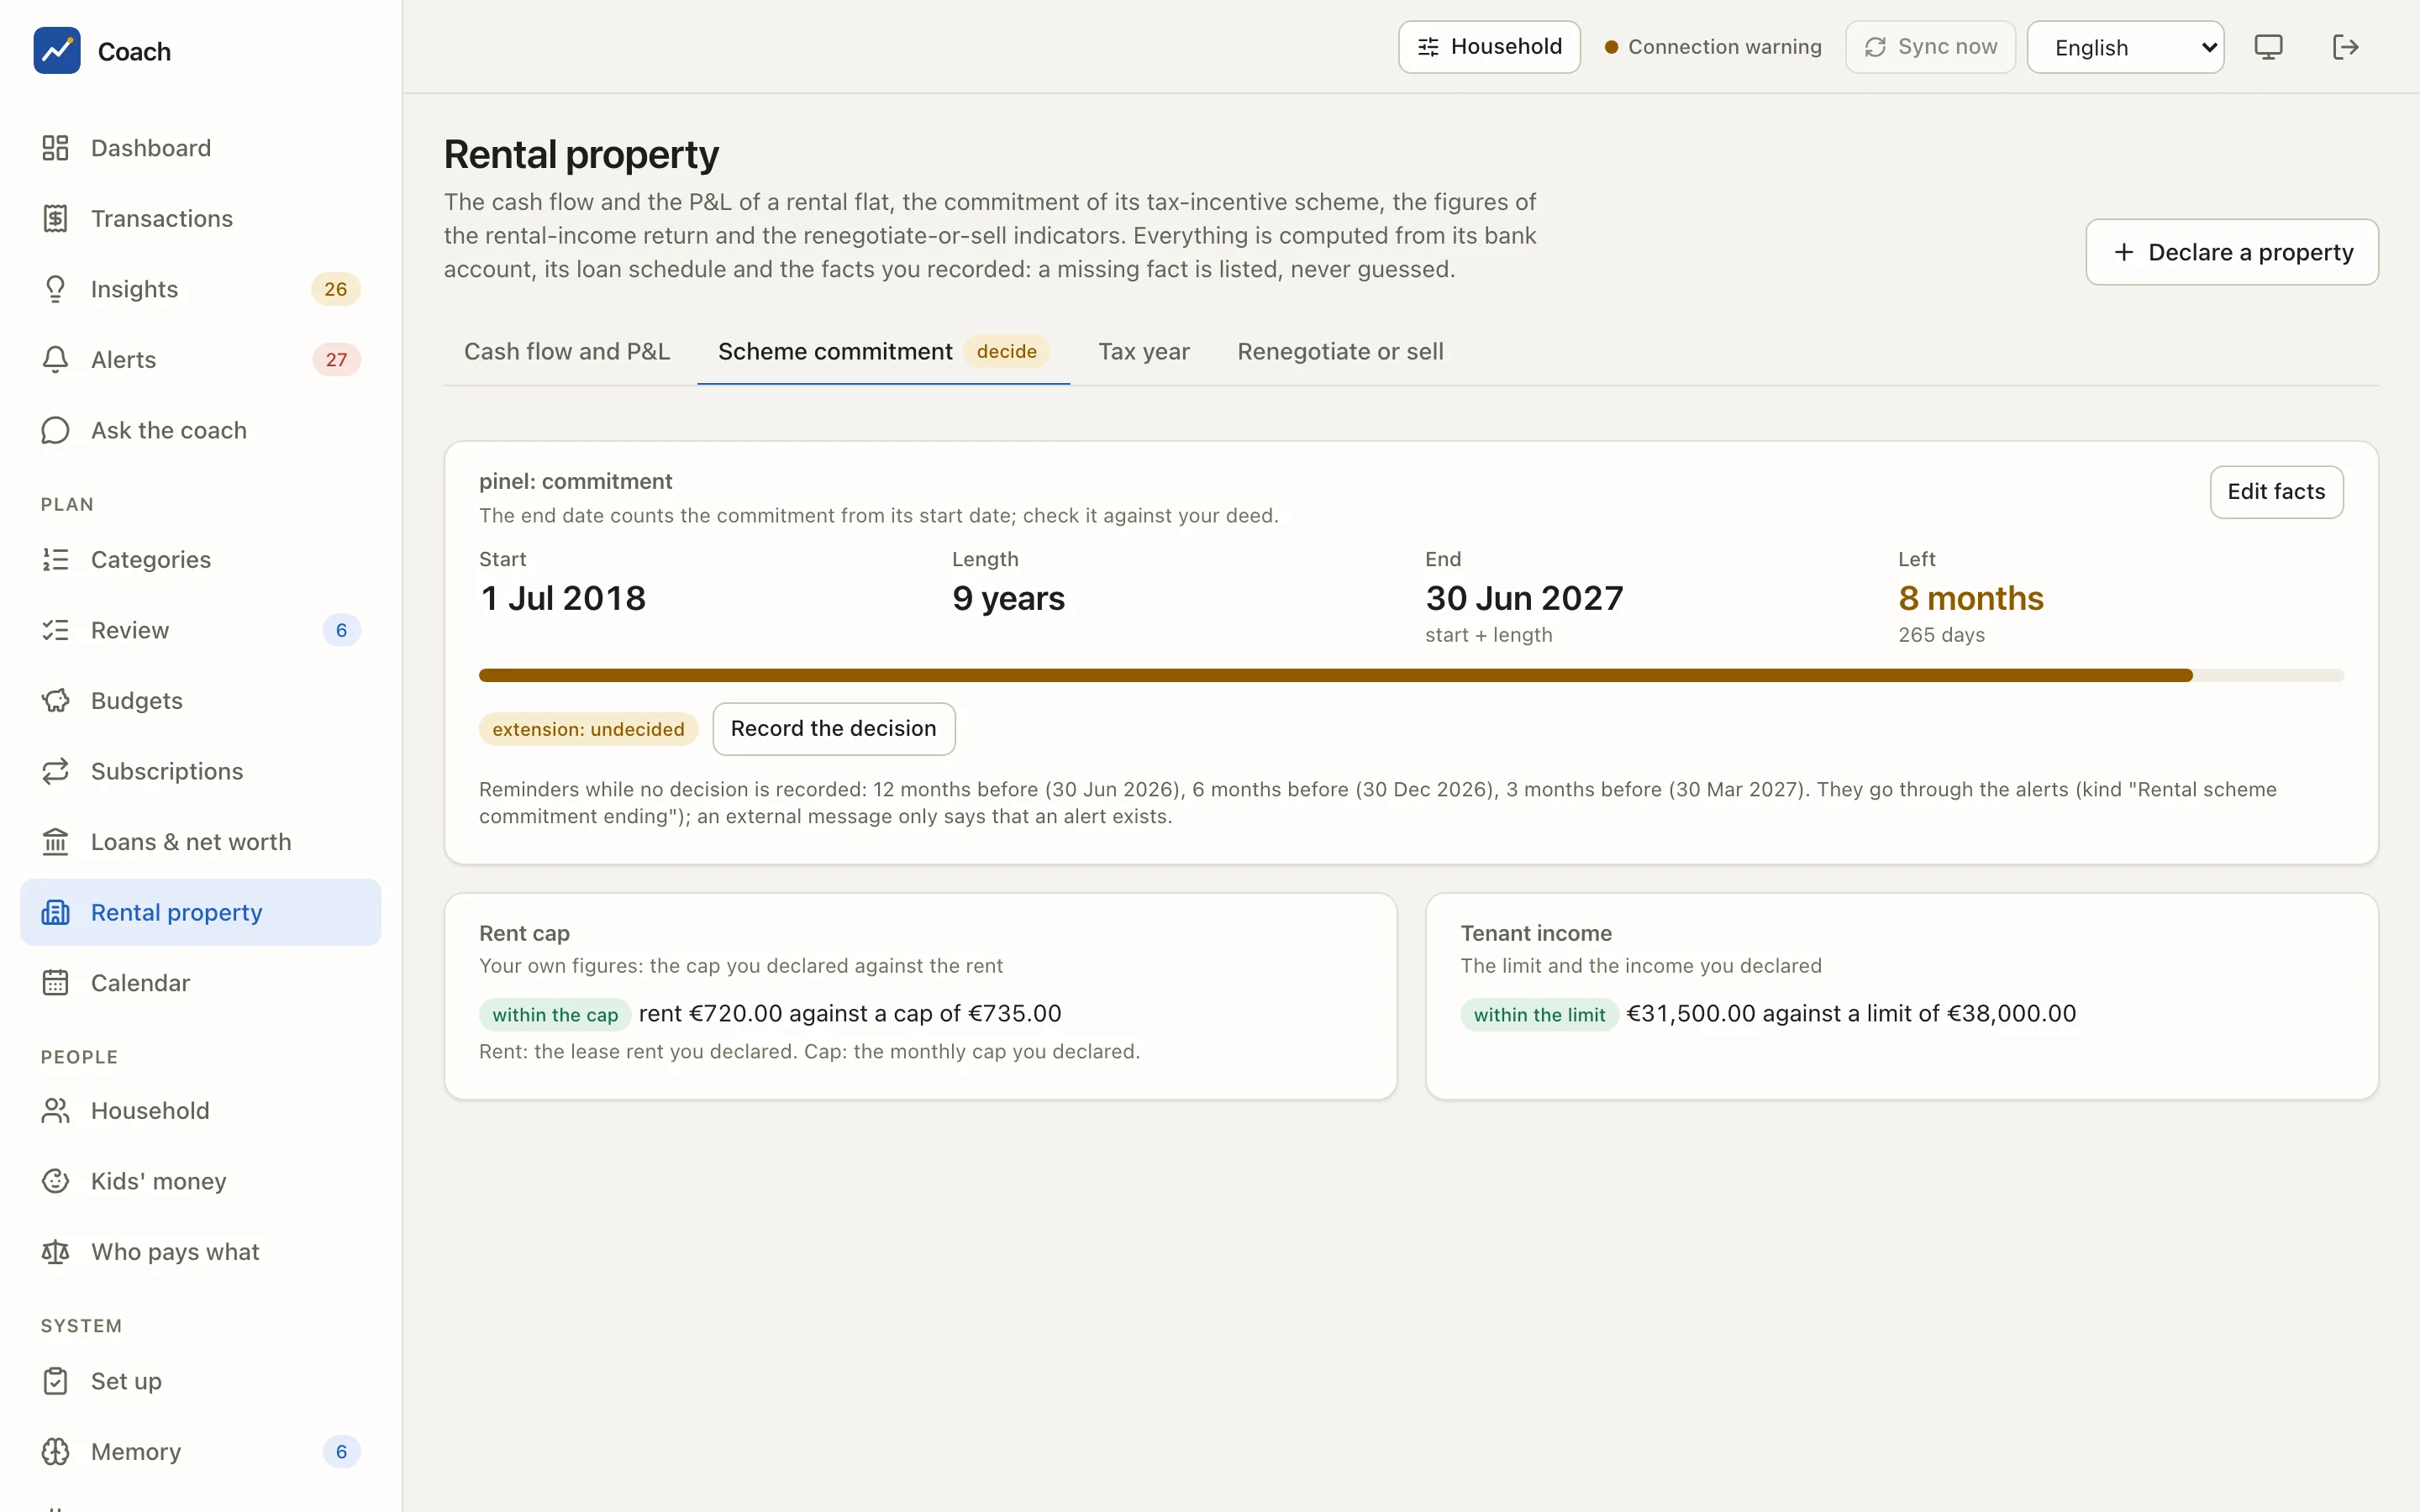
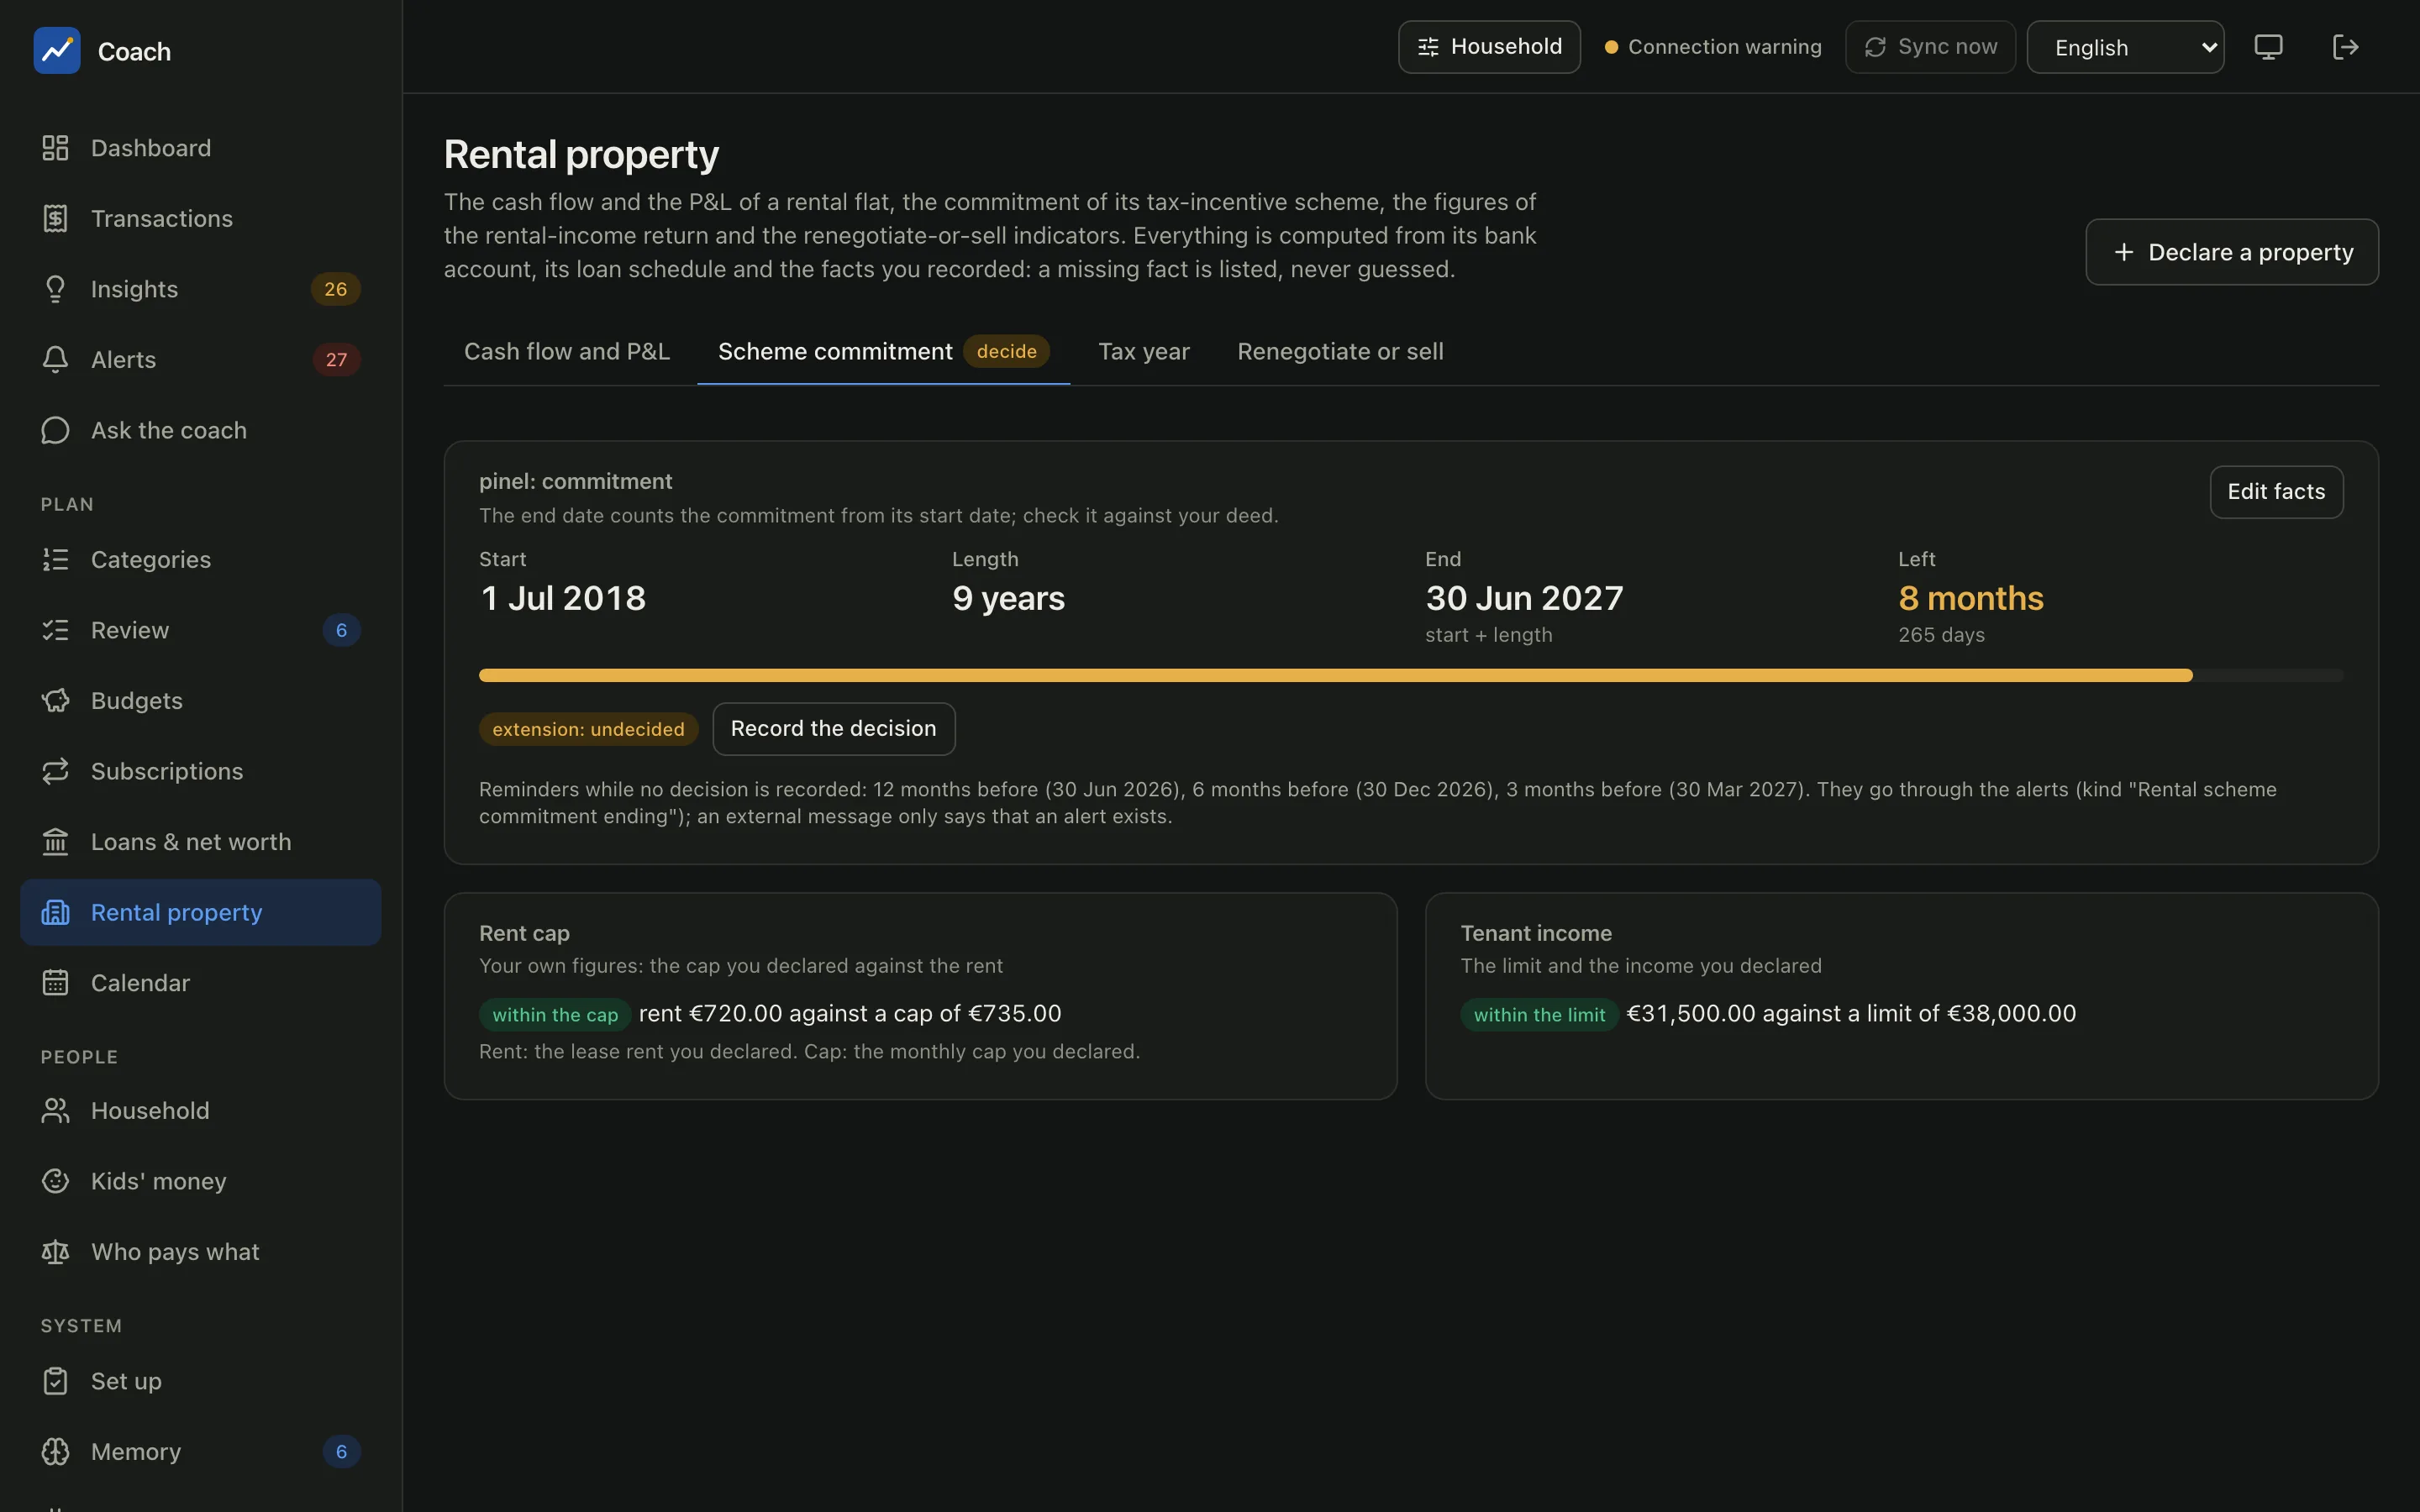
- Start, Length, End (start + length; check it against your deed) and the time Left, with a progress bar.
- Reminders 12, 6 and 3 months before the end while no decision is recorded. They go through the alerts; an external message only says that an alert exists. Record the decision (extend or not) stops them.
- Rent cap: the lease rent against the cap you declared ("within the cap").
- Tenant income: the tenant's income against the limit you declared ("within the limit").
- Facts the coach does not know: what is missing to check the commitment, also asked as an open question.
Tax year
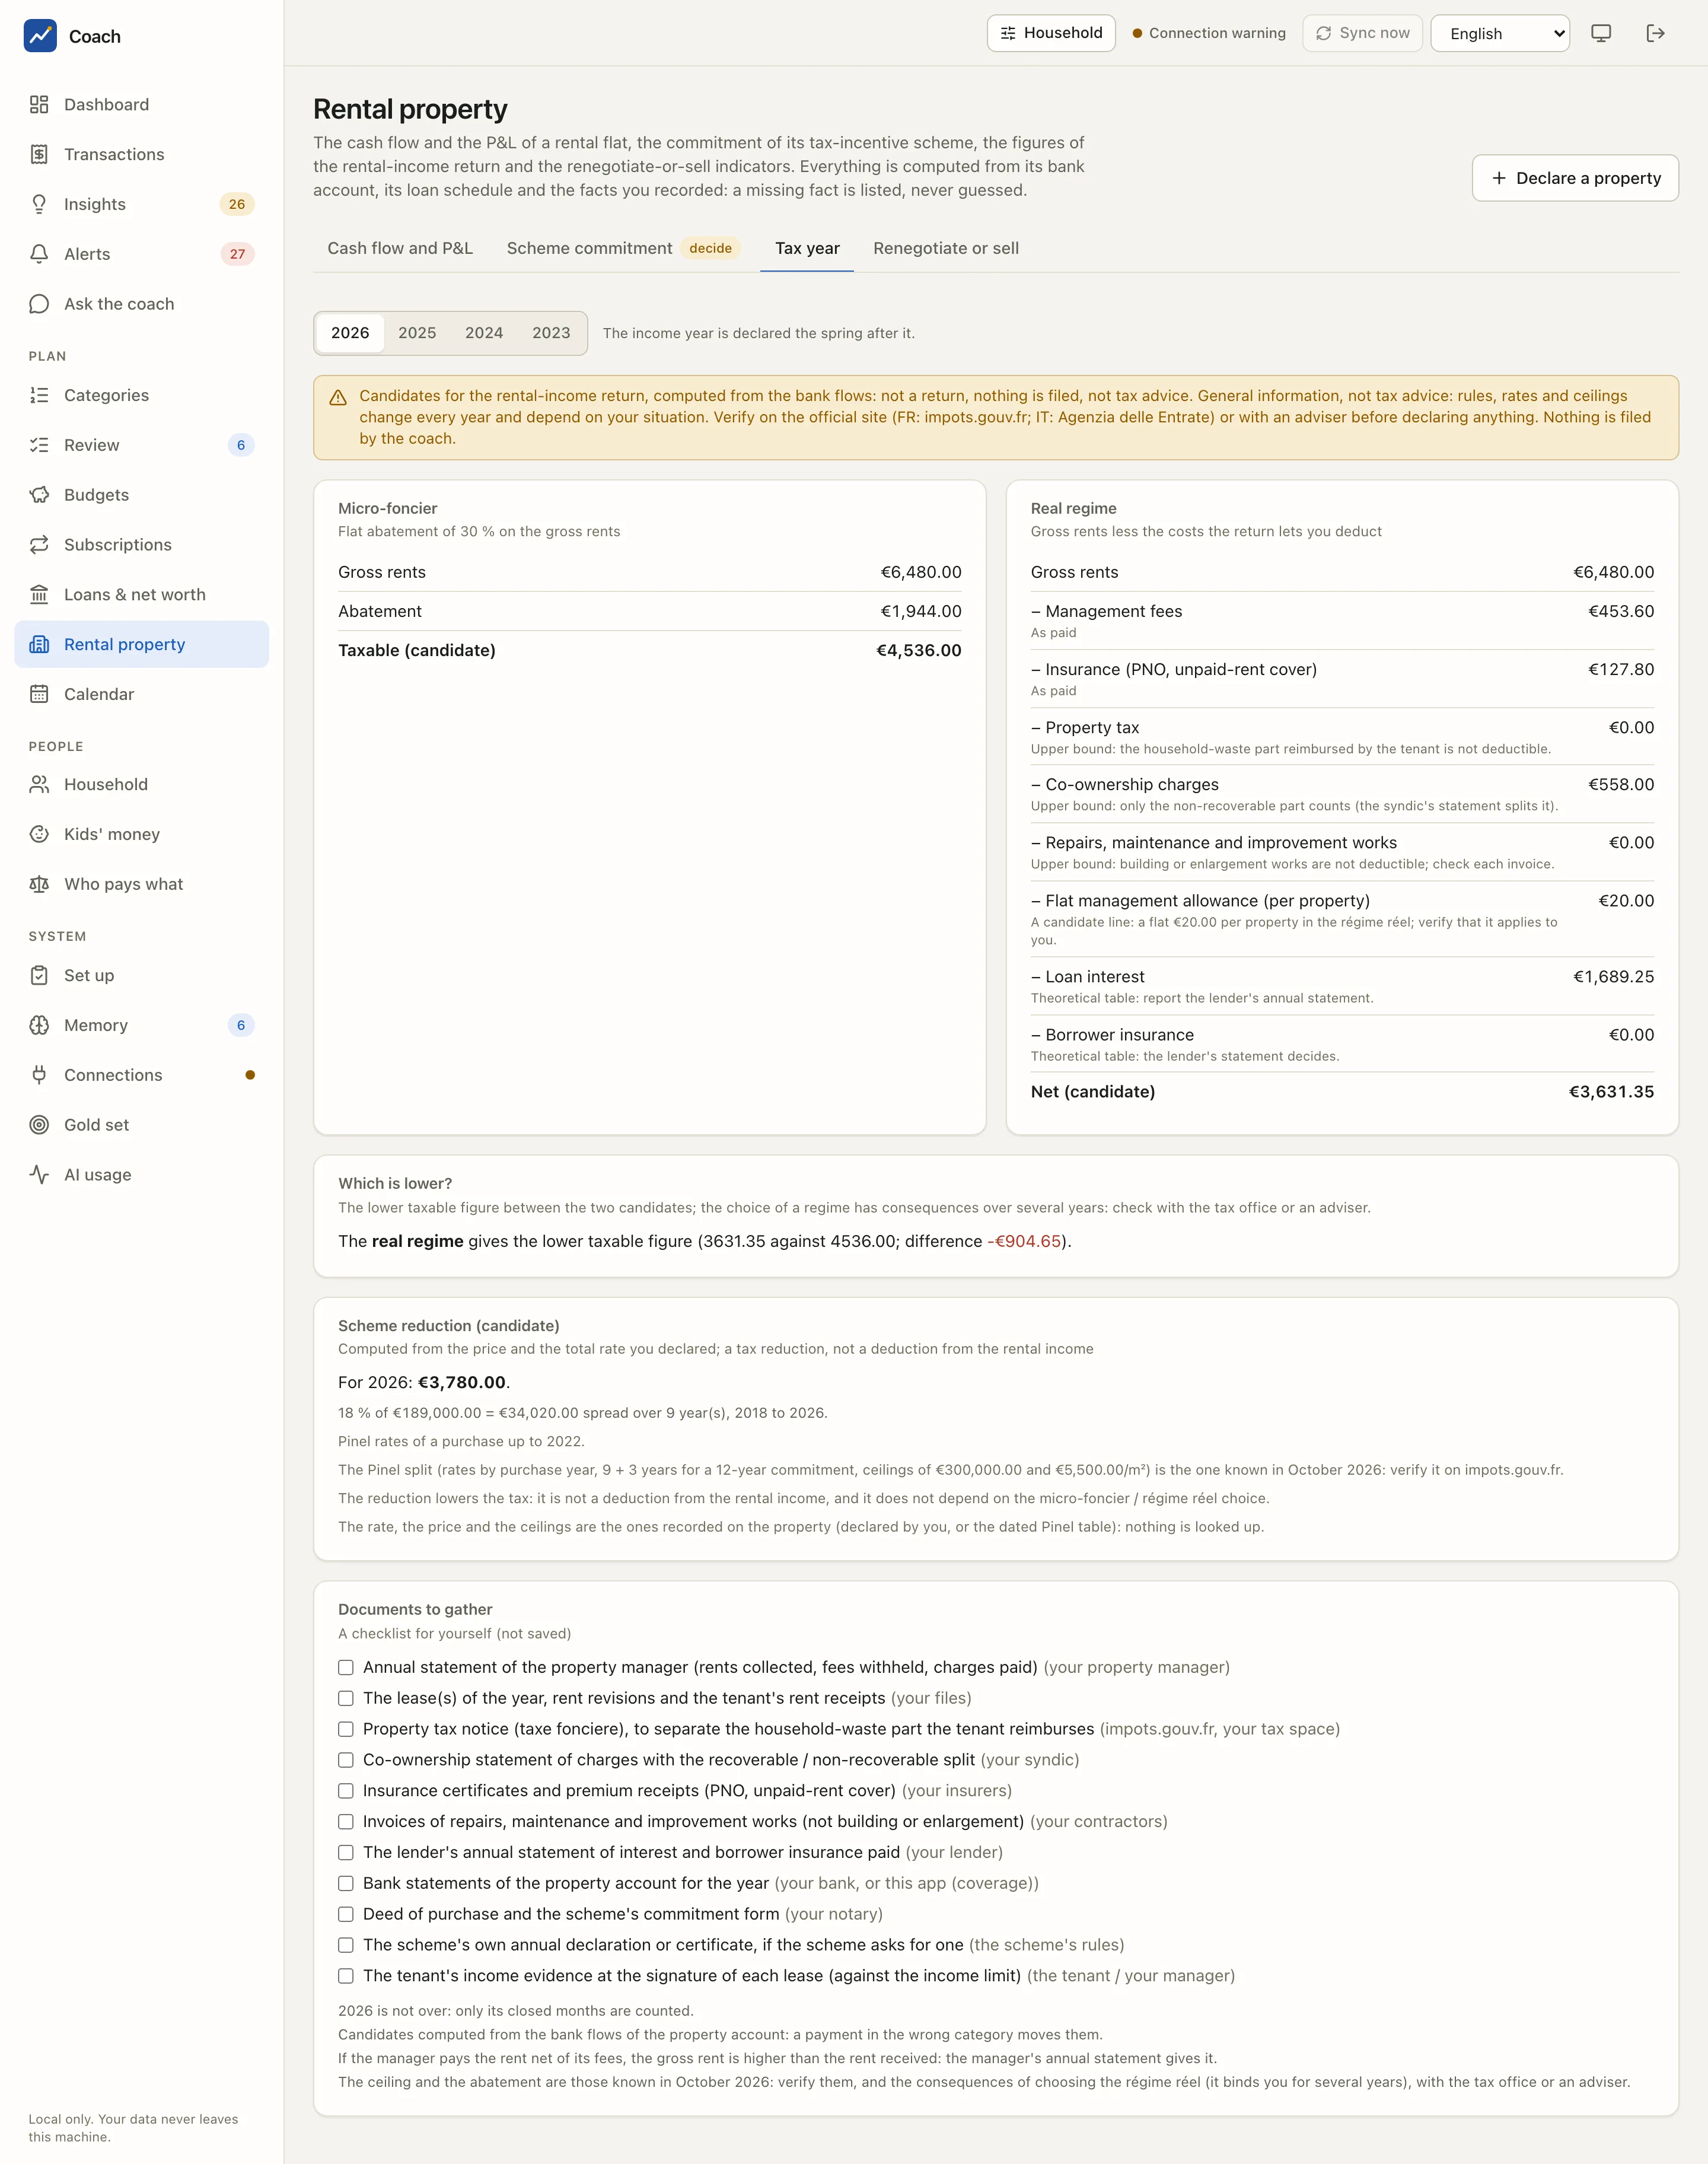
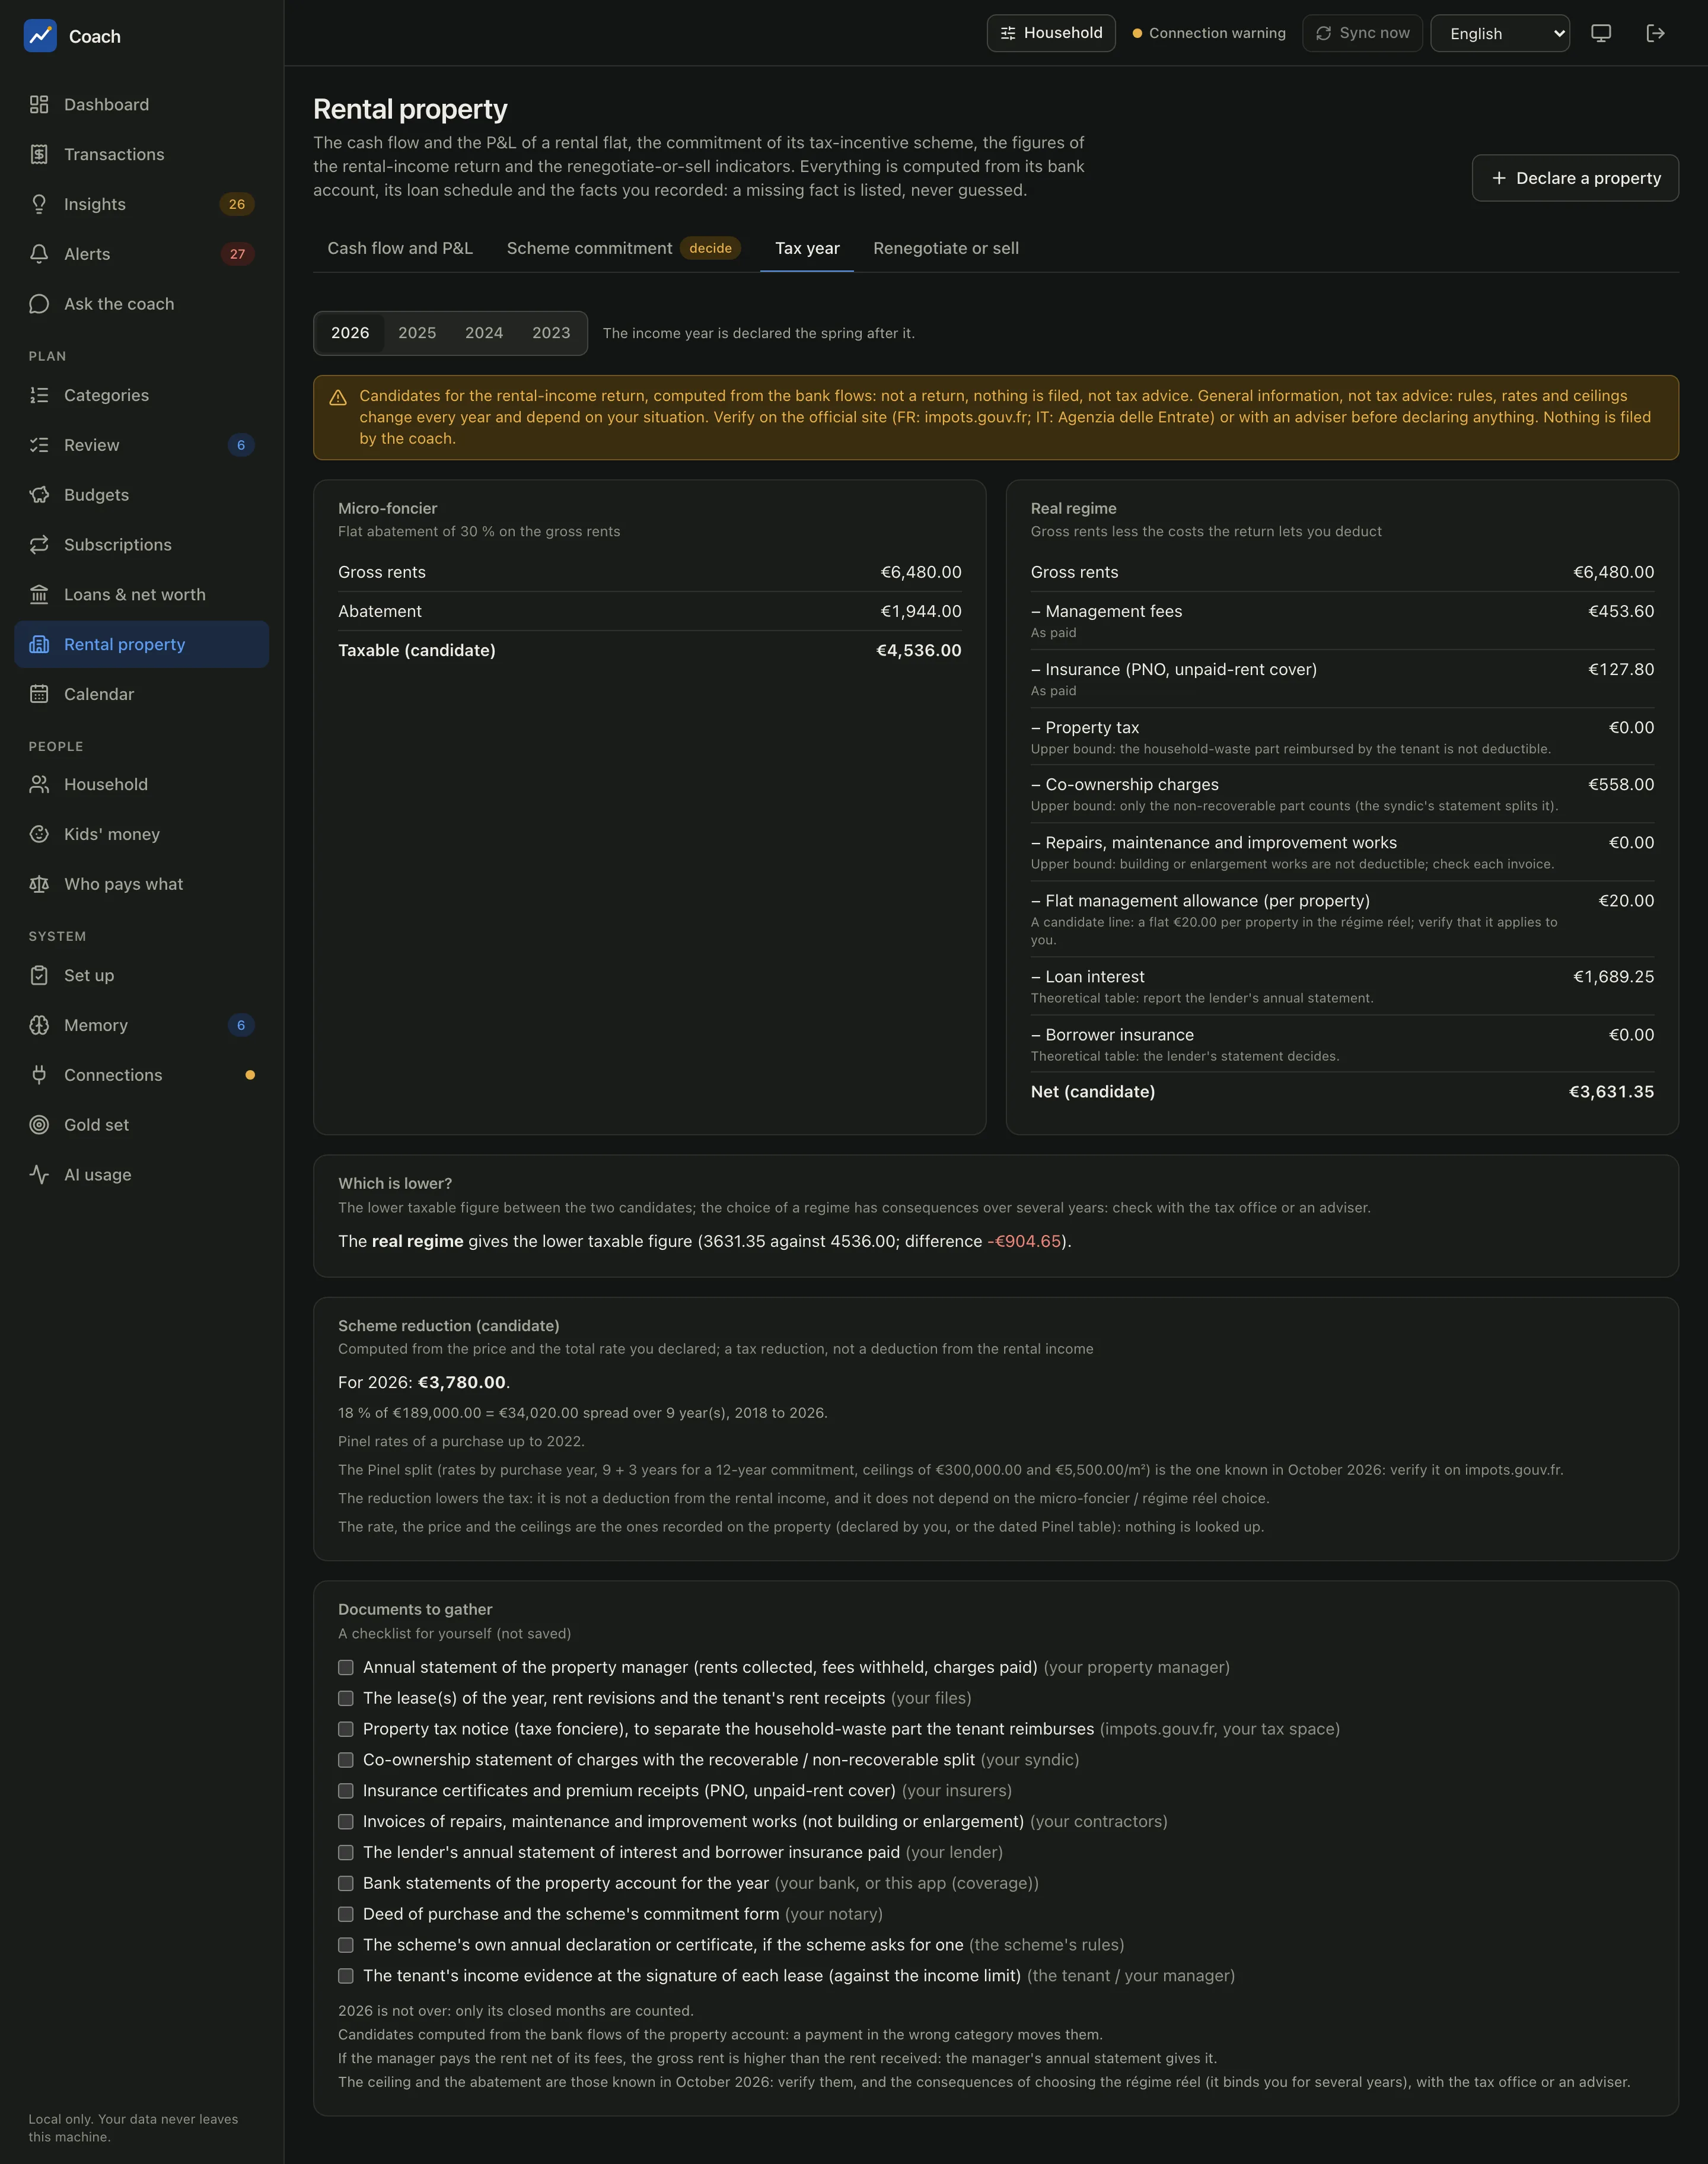
Pick the income year (it is declared the spring after it). The page computes candidates for the French rental-income return:
| Card | What |
|---|---|
| Micro-foncier | gross rents less the flat 30 % abatement |
| Real regime | gross rents less the deductible costs: management fees, insurance, property tax, co-ownership charges, works, the flat management allowance, and the loan interest and borrower insurance from the schedule |
| Which is lower? | the lower taxable figure and the difference |
| Scheme reduction (candidate) | from the price and the rate you declared: a tax reduction, not a deduction from the rental income |
| Documents to gather | a checklist for yourself (not saved) |
Several real-regime lines are upper bounds (only part of the charges, the property tax or the works may be deductible: the syndic's statement and the invoices decide), and the interest comes from the theoretical table: report the lender's annual statement.
Not a return, nothing is filed, not tax advice
These are candidates computed from the bank flows. Rules, rates and ceilings change every year and depend on your situation, and choosing the real regime binds you for several years. Verify on the official site (impots.gouv.fr in France) or with an adviser before declaring anything. The Italian return is not modelled.
Renegotiate or sell
Facts with a neutral reading, never a recommendation:
- Market rate: a rate you looked up for a loan of similar duration, with its date. A rate older than 30 days, or without a date, is flagged.
- Loan rate vs market: the loan's rate against it. When the gap is at least 0.5 points, the page says a quote may be worth asking for and prices a Renegotiation on the real schedule with the fees you give (your bank or a broker gives the binding figure).
- End of the commitment: its date, the months left, and a reminder that ending a scheme early can call the advantage into question.
- Net equity: the value you declared minus the capital still due, with the loan-to-value ratio. It is before selling costs, the early-repayment penalty and any capital-gains tax, none of which is modelled.
The app never says to sell, keep or switch, and names no lender or product. General information, not financial advice.
From the terminal
uv run coach rental list
uv run coach rental cashflow
uv run coach rental pnl --year 2026
uv run coach rental scheme
uv run coach rental tax --year 2026
uv run coach rental indicators
uv run coach rental flows          # flows in no property category, to label
coach rental add, edit, extension, vacancy and market-rate preview the change and write after a typed yes in your terminal.
See also
- Rental property reference: the model, the rules, the scheme and the tax-year maths.
- Loans & net worth: the loan behind the property.
- Insights & alerts: commitment reminders and rent not received.